Business Concepts
Tax Loss Harvesting (2026): Cut Your Tax Bill With Losses
Tax loss harvesting lets you offset capital gains with investment losses and deduct up to $3,000 a year. Learn the rules, wash-sale traps, and a real example.
Tax loss harvesting turns a paper loss into a legitimate tax deduction. You sell an investment that has dropped in value, lock in the loss for tax purposes, and use it to offset gains elsewhere in your portfolio. Done right, it is one of the few tax strategies that costs you nothing but timing.
Quick answer
Tax loss harvesting means selling an investment at a loss on purpose, then using that loss to offset capital gains or up to $3,000 of ordinary income on your tax return. Any leftover loss carries forward to future years, and the wash-sale rule blocks you from buying back a substantially identical security within 30 days.
Disclaimer: This article is general information, not tax advice. Tax rules differ by location and situation and change frequently. Consult a licensed tax professional or accountant.
Key takeaways
- Losses offset capital gains dollar for dollar, then up to $3,000 of ordinary income per year.
- Unused losses carry forward indefinitely, so a bad year can still pay off tax-wise years later.
- The wash-sale rule voids the deduction if you rebuy a substantially identical security within 30 days before or after the sale.
- Short-term losses offset short-term gains first, which matters because short-term gains are taxed at higher ordinary rates.
- Robo-advisors and brokerages now automate harvesting daily, but you can do it manually in any taxable brokerage account.
What Is Tax Loss Harvesting?
Tax loss harvesting is the practice of selling a security at a loss to reduce your taxable capital gains, then reinvesting the proceeds in a similar but not identical asset. It only applies to taxable brokerage accounts, since IRAs and 401(k)s have no capital gains tax to offset.
Tax loss harvesting sits alongside other core business and finance concepts that every investor should understand before building a long-term portfolio.
The IRS treats every sale of stock, a fund, or a bond as a taxable event. If the sale price is below what you paid, you realize a capital loss. That loss becomes useful the moment you have gains to offset, whether from the same account or a different one.
Tax Loss Harvesting Explained
The mechanics run on three IRS rules. First, losses offset gains of the same type: short-term losses against short-term gains, long-term against long-term. Any leftover loss then crosses over to offset the other type.
Second, after gains are fully offset, you can deduct up to $3,000 of ordinary income per year ($1,500 if married filing separately), according to IRS Topic No. 409. Losses beyond that carry forward to future tax years with no expiration date.
Third, the wash-sale rule under IRS Publication 550 disallows the loss if you buy a substantially identical security within 30 days before or after the sale, a 61-day window in total.
Investors dodge the wash-sale trap by buying a similar but not identical fund, say swapping one S&P 500 index fund for another that tracks a different index, then waiting out the 30-day window before returning to the original if they want it back.
Automated platforms made this practical for everyday investors. Robo-advisors added a layer of algorithmic reintermediation to portfolio management, scanning accounts daily for harvestable losses instead of waiting for an advisor to notice.
Tax Loss Harvesting Examples
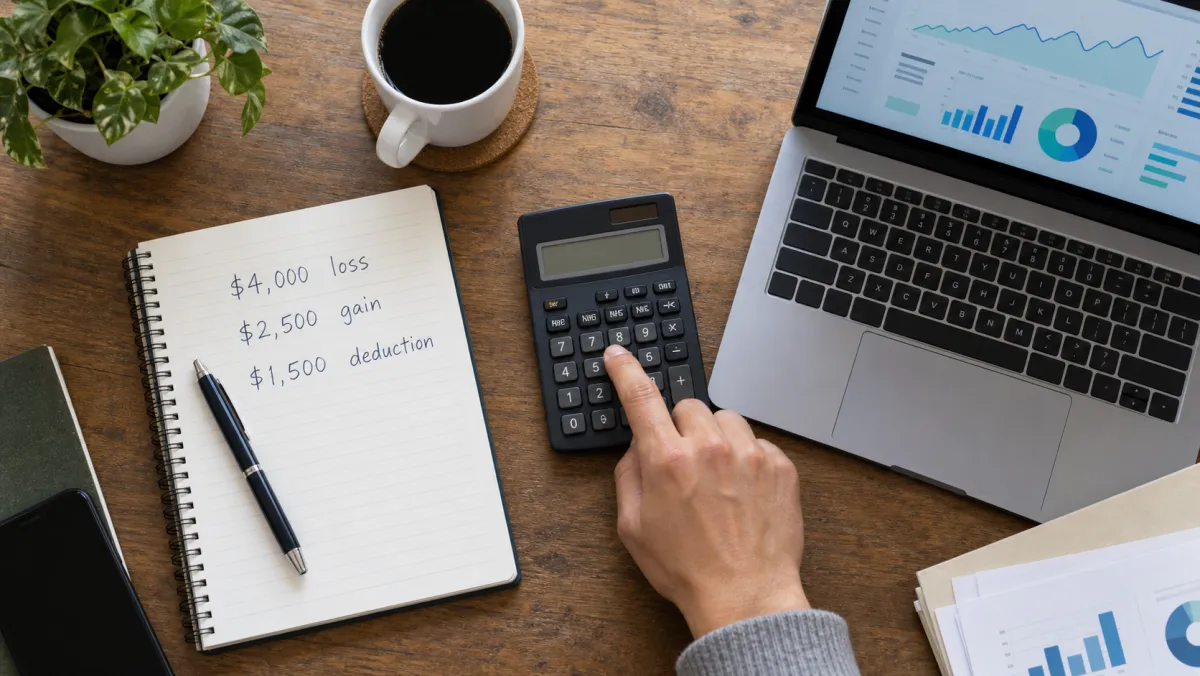
Say you bought $20,000 of a technology fund that is now worth $16,000, a $4,000 unrealized loss. You also sold a different holding earlier in the year for a $2,500 long-term gain. Harvesting the tech fund loss wipes out that gain entirely.
The remaining $1,500 loss then applies to ordinary income, since it is under the $3,000 annual cap. If your loss had been $8,000 instead, you would deduct $3,000 this year and carry the remaining $2,500 into next year's return.
| Scenario | Realized Loss | Used Against Gains | Deducted vs. Income | Carried Forward |
|---|---|---|---|---|
| Small loss | $4,000 | $2,500 | $1,500 | $0 |
| Large loss | $8,000 | $0 | $3,000 | $5,000 |
| No gains that year | $3,000 | $0 | $3,000 | $0 |
The payoff is not theoretical. Research from Parametric, the asset manager formed after Aperio Group's tax-optimization studies, found that systematic harvesting added roughly 1% a year in aftertax return for taxable equity portfolios over multi-year periods.
A loss you never realize on paper is just a loss. A loss you sell on purpose is a tax deduction.
How to Apply Tax Loss Harvesting
Review your taxable accounts for positions trading below your cost basis, ideally every quarter and again in December before the tax year closes. Most brokerages show unrealized gain or loss right in the account dashboard.
Sell the losing position and immediately reinvest in something similar enough to hold your market exposure, but not identical enough to trigger the wash-sale rule. A different fund tracking a different index works, buying back the same ETF the next day does not.
Log the trade date, cost basis, and sale price. Your broker issues a 1099-B, but matching gains and losses across multiple accounts is your responsibility, especially if you also hold shares in a spouse's account or an IRA.
Repeat the review near year-end, since December is when most investors harvest losses to lock in the deduction before the tax year closes on December 31.
Common Tax Loss Harvesting Mistakes
Triggering a wash sale by accident is the most common error, often because an automatic dividend reinvestment quietly rebuys the same fund inside the 30-day window. Turn off automatic reinvestment before you harvest.
Another mistake is harvesting losses inside a tax-advantaged account like a 401(k) or IRA, where there is no capital gains tax to offset in the first place. The strategy only works in taxable brokerage accounts.
Chasing every small loss also backfires once trading costs and time add up. Most advisors suggest harvesting when the loss exceeds a meaningful threshold, often a few hundred dollars or more, not every minor dip.
Should You Automate It?
Robo-advisors like Betterment and Wealthfront run daily automated harvesting, which catches more opportunities than a quarterly manual review. But automation adds its own benefits and risks of innovation, including fees, less control over which lots get sold, and the chance of harvesting too aggressively near a rebalance.
The same discipline that helps you spot the signs you are being set up to fail at work, tracking patterns instead of reacting emotionally, applies here. A rules-based harvesting calendar beats ad hoc selling driven by a bad week in the market.
Tax Loss Harvesting: FAQ
Does tax loss harvesting really save money?
Yes, it lowers your current tax bill by offsetting gains and up to $3,000 of ordinary income each year, and the effect compounds when you reinvest the tax savings instead of spending them.
What is the wash sale rule in tax loss harvesting?
The wash-sale rule blocks the deduction if you buy a substantially identical security within 30 days before or after the sale, covering a 61-day window in total.
Can you tax loss harvest every year?
Yes, there is no limit on how often you harvest, and many investors review positions quarterly with a final pass every December before the tax year closes.
Is tax loss harvesting worth it for small portfolios?
It still helps, since even a $1,000 loss reduces taxable income dollar for dollar, though the time spent tracking trades matters more as portfolio size shrinks.
What is the tax loss harvesting limit?
There is no cap on losses used against capital gains, but only $3,000 a year applies against ordinary income, with the rest carried forward indefinitely.
This content is for general informational purposes only and is not tax advice. Consult a qualified tax professional or accountant about your specific circumstances.