Business Concepts
Statement Of Retained Earnings: Formula + Example (2026)
See the exact formula for a statement of retained earnings, a worked two-quarter example, and how it connects to your P&L and cash flow.
A statement of retained earnings tracks how much profit a company has kept and reinvested instead of paying out as dividends. It sits alongside other core business concepts every finance professional needs, connecting the income statement and the balance sheet by answering one question: where did the profit go?
Quick answer
A statement of retained earnings shows the change in a company's retained earnings over a period. It starts with the beginning balance, adds net income from the profit and loss statement, subtracts dividends paid, and arrives at the ending retained earnings balance reported on the balance sheet.
Key takeaways
- Formula: beginning retained earnings plus net income, minus dividends, equals ending retained earnings.
- It links directly to the profit and loss statement and the balance sheet, never the income statement alone.
- Sole proprietors and partnerships often use a statement of owner's equity instead of retained earnings.
- A negative balance, called an accumulated deficit, signals the company has paid out or lost more than it earned.
- Reading it alongside the statement of cash flows shows whether reported profit turned into real cash.
What Is Statement Of Retained Earnings?
The statement of retained earnings shows how a company's accumulated profit changes from one accounting period to the next. The formula is direct: beginning retained earnings plus net income, minus any dividends paid, equals ending retained earnings. That ending figure then flows into the equity section of the balance sheet, not the income statement.
That treatment is defined under U.S. GAAP by the Financial Accounting Standards Board in ASC Topic 505, which governs how companies report equity and dividend activity. Investors read the resulting balance to judge whether management reinvests profit into growth or returns cash to shareholders.
Statement Of Retained Earnings Explained
The profit and loss statement definition is straightforward: it lists revenue, cost of goods sold, operating expenses, and the resulting net income or loss for a period. The profit and loss statement meaning goes further, though. It represents operating performance, while the statement of retained earnings shows what happened to that performance afterward.
Net income from the profit and loss statement is only the starting point, not the same thing as cash. The statement of cash flows reconciles it against real cash movement, and the U.S. Securities and Exchange Commission requires public companies to include it as one of three primary financial statements in every annual Form 10-K.
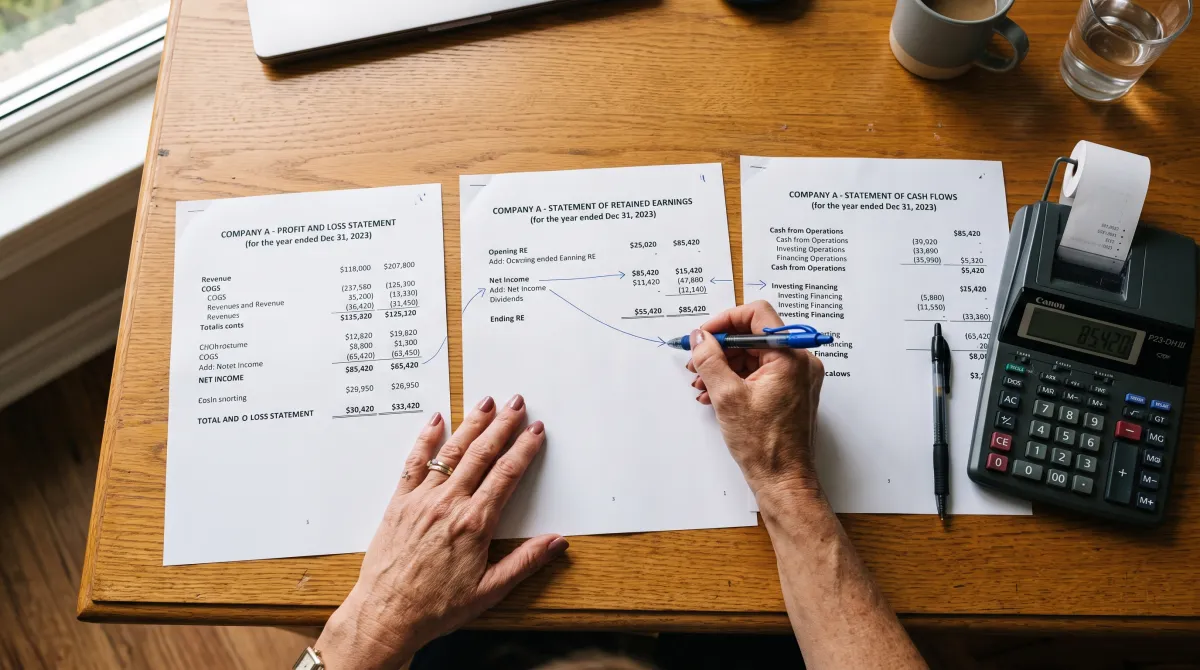
Where It Fits Among Your Other Financial Statements
There are two common types of profit and loss statement: single-step, which subtracts total expenses from total revenue in one calculation, and multi-step, which separates operating and non-operating activity before arriving at net income. Multi-step versions are more useful when building the retained earnings roll-forward, because they isolate the operating profit that actually drives reinvestment.
The benefits of profit and loss statement reporting extend beyond taxes. It shows lenders whether a business can service debt, helps owners spot margin erosion early, and gives the retained earnings calculation a clean net income figure to start from each period.
Sole proprietors and partnerships typically skip retained earnings and use a statement of owner's equity instead, since there is no separate corporate entity holding the profit. The IRS Schedule C (Form 1040) is the standard profit and loss statement template U.S. sole proprietors use to report that income at tax time.
Businesses raising capital or planning a launch often build a proforma financial statement first, projecting retained earnings under a few growth scenarios before the real numbers exist. That forward model matters even more when the business itself is changing, for example through reintermediation, since new sales channels shift how quickly profit accumulates.
Statement Of Retained Earnings Examples
Numbers make the connection between statements clearer than definitions do. Here is a two-quarter walkthrough showing how one dollar of profit moves from the profit and loss statement through retained earnings and into the statement of cash flows.
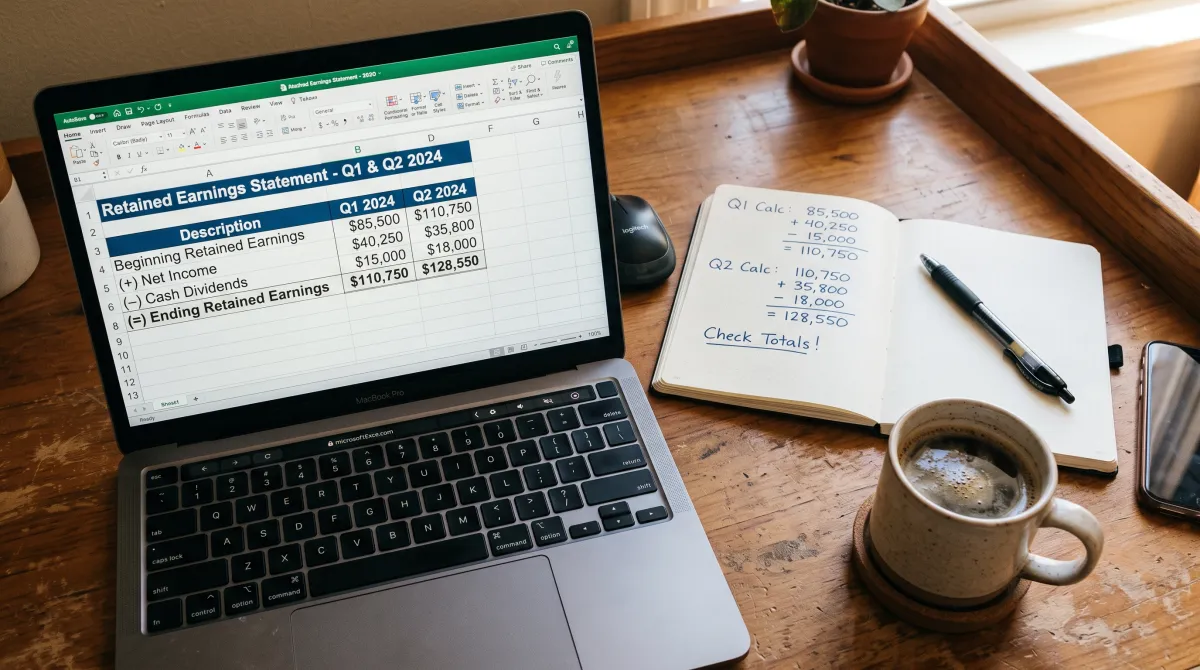
| Quarter | Beginning RE | Net income | Dividends paid | Ending RE |
|---|---|---|---|---|
| Q1 | $150,000 | $42,000 | $10,000 | $182,000 |
| Q2 | $182,000 | $38,500 | $10,000 | $210,500 |
That $210,500 ending balance is the figure that lands on the balance sheet under stockholders' equity. It is also the number a lender or investor checks first when they want to know whether two quarters of reported profit actually stuck, rather than getting paid out or absorbed by losses elsewhere in the business.
How to Apply Statement Of Retained Earnings
A few profit and loss statement best practices carry over directly into retained earnings work. Reconcile net income to the cash flow statement every period, not just at year end. Flag any dividend or distribution the moment it is approved, so the roll-forward never lags the board minutes.
Common profit and loss statement techniques, like trend analysis across trailing twelve months and variance analysis against budget, also sharpen the retained earnings figure. They catch the kind of one-time gain or expense that would otherwise distort next period's starting balance.
Profit and loss statement interview questions show up often in finance and operations interviews. Most ask a candidate to walk through the formula from memory or explain a swing in net income between two periods.
Reading profit and loss statement in the workplace signals matters too. A manager who quietly pads dividends before a performance review, while the numbers on paper do not match what you were told verbally, is one of the signs you are being set up to fail at work.
Documenting the benefits and risks of innovation before a major product launch also helps finance model dividends conservatively, since new product lines rarely generate stable profit in their first year.
Reviewing the statement of retained earnings every quarter, not just annually, catches problems while they are still cheap to fix. It takes ten minutes once the profit and loss statement and cash reconciliation are already done.
Retained earnings is the one number that proves whether profit was real or just paper.
Related guides
Statement Of Retained Earnings: FAQ
What is a profit and loss statement?
A profit and loss statement, also called an income statement, reports a company's revenue, expenses, and net income or loss over a specific period, typically a month, quarter, or year. Small businesses often prepare it monthly, while larger companies typically report it quarterly and annually.
What are some profit and loss statement examples?
A simple example lists revenue at the top, subtracts cost of goods sold and operating expenses, and ends with net income; a multi-step example adds a separate operating income line before non-operating items like interest and taxes. Software companies frequently show a third format, contribution margin, which separates variable from fixed costs for unit economics.
Income statement vs balance sheet, what is the difference?
The income statement reports performance over a period, like a quarter, while the balance sheet reports financial position at a single point in time, including the retained earnings carried over from prior periods' income statements. Both statements come from the same accounting system, but only the balance sheet carries a running retained earnings balance forward.
What does a cash flow statement example look like?
A basic cash flow statement example separates cash from operating activities, like customer receipts, from investing activities, like equipment purchases, and financing activities, like loan proceeds or dividend payments. Free templates from accounting software providers usually pre-build these three sections so the numbers tie back to the general ledger automatically.
How to improve profit and loss statement accuracy?
The fastest way to improve profit and loss statement accuracy is to close the books on a consistent schedule, reconcile accounts before finalizing net income, and review actual results against a proforma financial statement or budget each period. Comparing budget to actual every month, rather than every quarter, usually surfaces the biggest accuracy gains fastest.